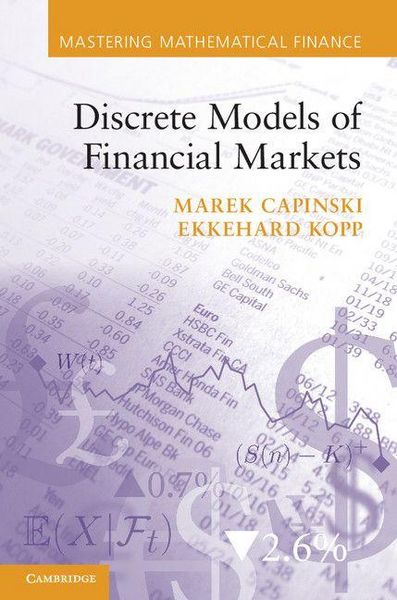
Discrete Models of Financial Markets
-
- Hardcover ausgewählt
- Taschenbuch
- eBook
-
Sprache:Englisch
Fr. 89.90
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Gebundene Ausgabe
Erscheinungsdatum
23.02.2012
Abbildungen
10 b/w illus. 95 exercises, Zeichnungen, nicht spezifiziert, Worked examples or Exercises
Verlag
Cambridge University PressSeitenzahl
192
Maße (L/B/H)
23.5/15.7/1.5 cm
Gewicht
437 g
Sprache
Englisch
ISBN
978-1-107-00263-0
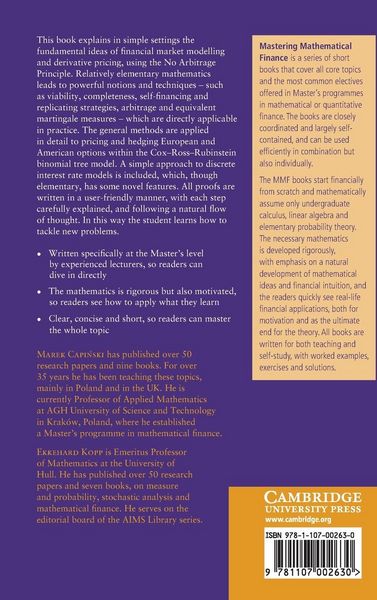
This book explains in simple settings the fundamental ideas of financial market modelling and derivative pricing, using the no-arbitrage principle. Relatively elementary mathematics leads to powerful notions and techniques - such as viability, completeness, self-financing and replicating strategies, arbitrage and equivalent martingale measures - which are directly applicable in practice. The general methods are applied in detail to pricing and hedging European and American options within the Cox-Ross-Rubinstein (CRR) binomial tree model. A simple approach to discrete interest rate models is included, which, though elementary, has some novel features. All proofs are written in a user-friendly manner, with each step carefully explained and following a natural flow of thought. In this way the student learns how to tackle new problems.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.